
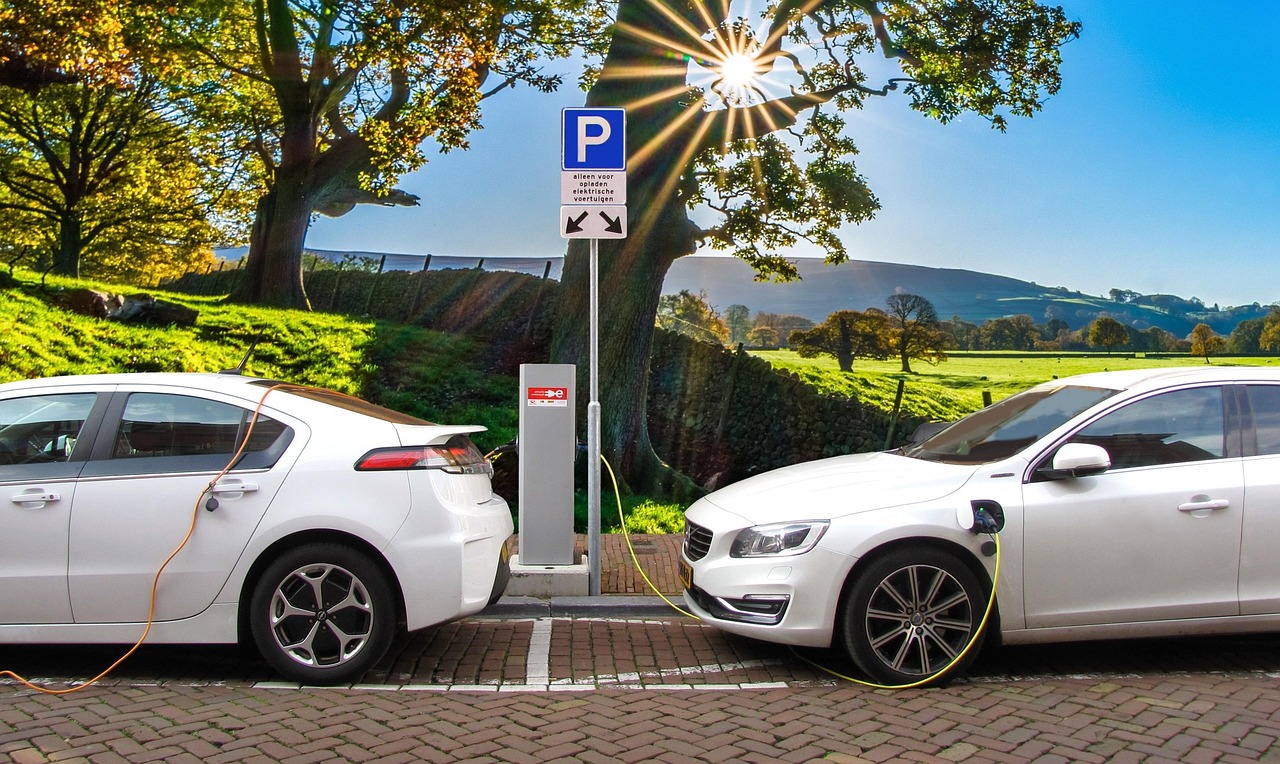
Fully Electric Company Cars - What Every Limited Company Director Needs To Know Before March 2027
If you're thinking about changing your company car, the next eighteen months are important.
There's a tax relief available right now that won't be around forever. And the detail of how you buy the car is just as important as the decision to buy it.
Here's everything you need to know before you act.
The 100% first-year capital allowance
If your company incurs qualifying expenditure on a new unused fully electric car by 31st March 2027, it can claim a 100% first-year capital allowance.
That means the full qualifying cost of the car can be deducted from your company's taxable profits in the accounting period the expenditure is incurred.
In real numbers. If your company spends £40,000 on a qualifying car, that £40,000 comes off your taxable profits. At a 25% Corporation Tax rate that's a £10,000 tax saving in the year of purchase.
Cars don't normally qualify for the Annual Investment Allowance or full expensing. This is a specific allowance for new fully electric cars and it's worth planning around.
The car has to qualify
Not every electric car qualifies. There are specific conditions.
The car must be fully electric. Plug-in hybrids do not qualify. The car must have certified CO2 emissions of 0g/km or be electrically propelled.
It must be new and unused. A small amount of delivery testing or demonstration mileage doesn't necessarily prevent a car qualifying but a second-hand car doesn't qualify for the 100% allowance. Writing-down allowances may still be available on second-hand electric cars but the immediate full deduction isn't.
How you buy it changes everything
This is where a lot of people get caught out.
Buying outright normally qualifies. Straightforward.
Hire purchase can qualify where the company is treated as owning the car. With qualifying HP, capital allowances may be available on the full capital cost once the car is brought into use - including amounts payable under future instalments. But the contractual and accounting classification matters. Not every HP agreement works the same way.
Ordinary lease or contract hire works differently. The leasing company generally claims the capital allowances. Your company gets Corporation Tax relief on the rental payments over the lease term instead. Different rules can apply to long funding leases.
Before you sign anything get the structure checked. The wrong contract type could mean missing the allowance entirely.
The deadline is not the order date
This is the most important point in this piece.
The 31st March 2027 deadline turns on when qualifying expenditure is incurred. Not when you order the car. Not necessarily when it's delivered.
Expenditure is generally incurred when the obligation to pay becomes unconditional. That's often on delivery but the contract and payment terms can change that date.
If you sign an order in January 2027 and your year end is March 2027 but the car isn't delivered until April 2027, you may miss the deadline entirely.
Of course, the relief could be extended at the Autumn Budget, as it has been before. But under the rules as they stand, it ends on 31 March 2027
Don't assume. Check the contract. Talk to us before you commit.
Charging equipment
The same 100% first-year allowance applies to new unused charging equipment installed by 31st March 2027 - where the equipment is installed solely for charging electric vehicles.
If you're setting up a home charging point or workplace charging as part of the decision this is worth factoring in.
Benefit-in-kind - the bit that catches people out
The capital allowance reduces your Corporation Tax bill. But there's a separate charge to consider if the car will be available for private use.
Private use includes commuting. The benefit-in-kind charge arises where private use is available - even if the driver does very little actual private mileage. There is no charge only where private use is genuinely prohibited and doesn't happen.
For a fully electric car the benefit-in-kind rate is 4% for 2026/27. That's 4% of the car's list price including taxable accessories. Not 4% of what the company actually pays for it.
So on a car with a list price of £50,000 the taxable benefit is £2,000. At a 40% personal tax rate that's £800 of income tax for the director. The company also pays Class 1A National Insurance on the benefit.
The rate is rising every year.
Tax Year | BIK Rate |
2026/27 | 4% |
2027/28 | 5% |
2028/29 | 7% |
2029/30 | 9% |
Still low compared to petrol or diesel cars. But factor it into the decision over the full life of the car.
Charging costs
Generally treated favourably.
There's usually no separate taxable benefit where the company pays to charge its company car. That includes qualifying workplace charging, a home charging point or reimbursement of charging costs.
Different rules apply if it's your own car rather than a company car.
One caution. Company-funded solar panels or home batteries are treated differently. They don't receive the same treatment as a charging point and can be taxable. Worth checking before you go further down that route.
VAT
VAT is a separate consideration and depends on how the car is acquired and whether it will be used privately.
For leased cars 50% of the VAT on rentals is normally blocked where private use is permitted. The rules differ between purchases and leases. This is worth specific advice based on your situation.
What to do before the deadline
Don't start with the car. Start with the numbers.
Talk to us before you sign anything. We'll compare outright purchase, hire purchase and leasing to work out which structure makes most sense for your situation. We'll check the contract, the delivery date, the date the car is brought into use and whether it genuinely qualifies.
The allowance is attractive. But the detail matters. A ten minute conversation before you sign could save a significant amount. A conversation after is much harder.
Thinking about a fully electric company car before the deadline? Get in touch before you commit to anything.
➡️ Click here to book a discovery call
The business you’re building deserves a finance function that can keep up with it.
Not sure if your current finance setup is right for where your growing business is going?
Take our free Business Finance Health Check and in just five minutes you'll discover what's working well, where the gaps are, and what to focus on next.
No jargon, just practical insight to help you build a stronger business.

FREE DOWNLOADS
A-Z of allowable business expenses
Download your A-Z guide of allowable business expenses.
Financial Housekeeping For Your Small Business
Download your guide to Financial Housekeeping For Your Small Business - ideal for start ups and early stage businesses
How to Scale Up your Business: Tips and Strategies for Success
Download your guide to How to Scale up your Business - ideal for slightly more established businesses that want to grow and scale their business
Don't want the guide?
But do want our regular email filled with tips and insights into business and how to maximise profit and grow your business?
Click here

Ready to take the stress out of finance?
Not quite ready to commit to a long term contract ? Book a value packed Power Hour for now at £180 Inclusive of VAT.
© 2023 All Rights Reserved | Sterling Financial Management Reg No 9780783,
Accounting, Bookkeeping and Business Advisory based in Dorking Surrey RH4 2JF
Reg Office : 71-75 Shelton Street, Covent Garden, London, WC2H 9JQ